




Slotine advises sponsors, investors and management teams on private equity transactions and acquisition finance across Hong Kong, Mainland China and Europe. From fund formation to portfolio acquisitions, leveraged buyouts and exits, our practice combines long-standing cross-border deal experience with deep Hong Kong regulatory and tax expertise.
We act as principal counsel on the legal, tax and regulatory aspects of the private equity lifecycle, including fund vehicles registered under Hong Kong law, SFC-licensed investment managers, acquisition financing structures and the carried interest tax concession.
Schedule 16D, Cap. 112
onshore HK regime since 31 Aug 2020
asset management for HK fund managers
Launching a fund, raising capital or executing a deal?
Scope your private equity matter with Maeva Slotine directly. Initial conversations are confidential and without obligation. International sponsors welcome — no travel to Hong Kong required.
Who we act for
- Private equity sponsors and general partners
- Limited partners and institutional investors
- Family offices and HNW co-investors
- Investment managers seeking SFC licensing
- Portfolio companies on bolt-on M&A
- Senior and mezzanine lenders
- Founders selling to PE buyers
What we deliver
- Fund formation and LPF registration
- Legal and tax due diligence
- SPA, SHA and management equity drafting
- Acquisition finance documentation
- Tax structuring (carry, FSIE, UFE)
- SFC Type 9 licensing support
- Exit and post-closing claims
How we support you across the private equity lifecycle
A private equity transaction is rarely a single event. Our team covers each stage of the lifecycle under one roof, with continuity of counsel from fund launch through to portfolio exit.
Slotine work: Sponsor structuring, LPF registration, SFC licensing
Key deliverables: LPA, side letters, subscription docs, Type 9 application
Slotine work: Private placement compliance, cross-border placement
Key deliverables: PPM review, marketing analysis, professional investor opinions
Slotine work: Legal and tax due diligence, transaction documents
Key deliverables: SPA, SHA, disclosure letter, management equity plan
Slotine work: Bolt-on M&A, board governance, refinancings
Key deliverables: Add-on SPAs, restructuring, intercreditor amendments
Slotine work: Trade sale, secondary, IPO readiness, distribution
Key deliverables: Sell-side SPA, W&I insurance, escrow, carry distribution
Sponsor and fund formation
We structure private equity, venture capital and growth funds using Hong Kong vehicles or cross-border structures, including the Limited Partnership Fund (LPF) regime under the Limited Partnership Fund Ordinance (Cap. 637), the Open-Ended Fund Company (OFC) and offshore alternatives. We draft the LPA, side letters, subscription documents and management agreements, and we coordinate SFC Type 9 licensing for fund managers based in Hong Kong.
Capital raising
We advise on private placement compliance, marketing restrictions under the Securities and Futures Ordinance, professional investor exemptions and cross-border placement into Mainland China and Europe. We also support GPs on co-investment vehicles, parallel funds and continuation vehicles.
Portfolio investments and bolt-on acquisitions
Once capital is deployed, we lead the transactional workstream: legal and tax due diligence, share purchase agreements, shareholders agreements, management equity packages, warranties and indemnities and completion mechanics. On bolt-on acquisitions, we coordinate with the portfolio company’s existing counsel to keep the deal on the sponsor’s timetable.
Exit strategies
Trade sales, secondary buyouts, dividend recapitalisations and IPO readiness work all fall within the practice. We negotiate sale and purchase documentation on the sell-side, manage W&I insurance processes and structure earn-outs, escrow and deferred consideration. We also advise on the tax treatment of carry distributions on exit.
Building a deal team for an active mandate? Slotine can scope fund, deal and finance workstreams in one engagement letter.
Acquisition finance and leveraged buyouts
Slotine acts on the financing side of acquisitions, both as borrower counsel for sponsors and as counsel to lenders on senior, mezzanine and unitranche structures. Hong Kong is a recognised hub for syndicated lending in Asia, and we work fluently with the LMA documentation standards used by regional and international banks.
Senior
Term loans, RCF, capex lines
LMA-style documentation, English or Hong Kong law.
Mezzanine
PIK notes, 2nd lien, preferred equity
Holdco-level structures with intercreditor coordination.
Security
Share charges, debentures, guarantees
Cross-border coordination with foreign counsel where needed.
Senior debt structures
Term loans, revolving credit facilities, capex facilities and acquisition lines, documented under English or Hong Kong law. We negotiate margin grids, covenants, baskets and equity cure mechanics on behalf of sponsors.
Mezzanine and subordinated debt
Holdco PIK notes, second lien facilities and preferred equity, with the intercreditor and subordination arrangements that go with them.
Security packages
Share charges over the target and intermediate holding companies, fixed and floating charges over Hong Kong assets, debentures, account control agreements and guarantees. We coordinate with foreign counsel where parts of the security package sit in Mainland China, Singapore or European jurisdictions.
Intercreditor arrangements
Negotiation of intercreditor and subordination deeds, equity cure rights, payment waterfalls and enforcement standstills.
PE-specific taxation in Hong Kong
Tax structuring is integral to fund and deal design, not an afterthought. Slotine works with sponsors on the points that drive after-tax returns.
Hong Kong is one of the few jurisdictions offering a 0% concessional rate on eligible carried interest, alongside a unified fund tax exemption and a Foreign-Sourced Income Exemption regime that, together, can deliver materially better after-tax returns than competing fund domiciles.
Carried interest tax concession
Under Schedule 16D of the Inland Revenue Ordinance, eligible carried interest paid by certified private equity funds qualifies for a 0% concessional Profits Tax rate for qualifying persons and a 100% deduction against Salaries Tax for qualifying employees. We advise sponsors and investment managers on HKMA certification, the qualifying conditions (including the substantial activities test) and ongoing substantiation.
Profits Tax exemption for funds
We structure funds to fall within the unified fund exemption regime and advise on the scope of qualifying transactions and incidental transactions.
Cross-border tax considerations
Use of Hong Kong’s treaty network for inbound and outbound investment, including access to Mainland China deal flow through the QFLP (Qualified Foreign Limited Partnership) and QDLP (Qualified Domestic Limited Partnership) programmes, and treatment of returns under the Foreign-Sourced Income Exemption (FSIE) regime.
Need a view on whether your fund qualifies for the carried interest concession? Initial assessment in a confidential call.
Regulatory framework
Hong Kong’s regulatory environment is sophisticated, principles-based and increasingly aligned with international standards. We help sponsors navigate it without losing commercial momentum.
Regulator: Securities and Futures Commission (SFC)
What we handle: Type 9 applications, RO arrangements, FMCC compliance, MIC regime
Regulator: Companies Registry
What we handle: Form LPF1 filing, AML responsible person, ongoing filings
Regulator: Inland Revenue Department
What we handle: Unified Fund Exemption claims, carry concession filings
Regulator: Hong Kong Monetary Authority
What we handle: Schedule 16D fund certification (currently under review)
Regulator: Companies Registry / SFC
What we handle: Responsible person framework, significant controllers register
Key deal documents we negotiate
From the first non-disclosure agreement to post-closing warranty claims, we draft and negotiate the full transaction architecture.
Why sponsors choose Slotine
How we work
- Founding partner involvement on every mandate
- Bilingual French and English practice
- Tax-led structuring from day one
- Direct line to the partner who pitched the work
- Pricing scaled to deal complexity, not firm overhead
Where we add value
- Cross-border M&A between Europe and Asia
- HK-PRC investment structuring
- Fund formation under LPF and OFC regimes
- Carried interest certification and substance
- Acquisition finance for mid-market deals
Your team
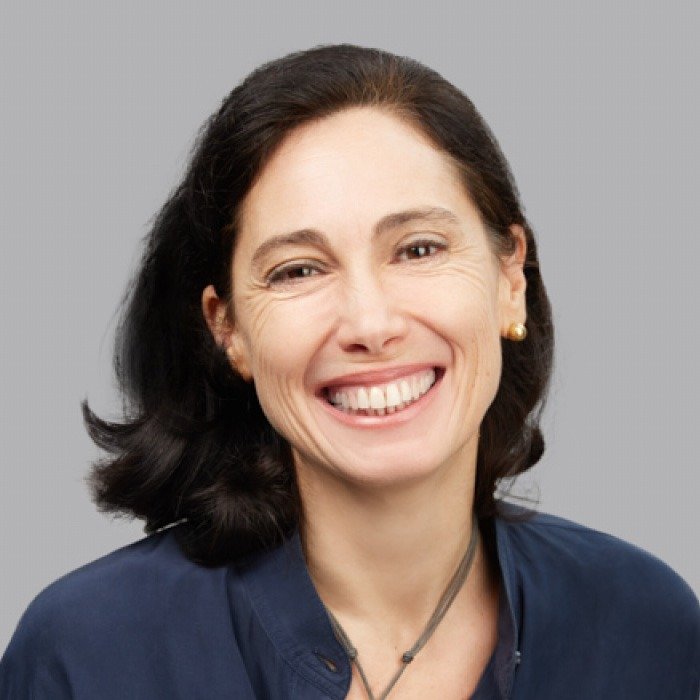
Maeva Slotine, Founding Partner, leads the Private Equity and Acquisition Finance practice. Her experience spans European leveraged buyouts, Asia-Pacific growth equity transactions and Hong Kong fund formation. Mathilde Chator supports the practice on M&A transactional execution.
Related insights and resources
Comparative guides
- Hong Kong Private Equity Guide (Mondaq, 2021)
- Hong Kong Private M&A Guide (Mondaq, 2025)
- Share charges and LBO debt security in Hong Kong
Articles and explainers
- Letter of Intent (LOI) in M&A: a drafting guide
- Limited Partnership Fund (LPF) Hong Kong
- Carried interest tax under Schedule 16D
- Legal and Tax Due Diligence practice
Frequently asked questions
Discuss your private equity or acquisition finance matter
If you are launching a fund, raising capital, executing a deal or arranging acquisition finance in Hong Kong, contact Maeva Slotine directly to scope the work. Initial conversations are confidential and without obligation.